In This Essay
I. The New Atomic Crude: Why Silicon Is the Foundation of Modern Sovereignty
Throughout the 20th century, industrial empires waged wars and redrew borders across the Middle East, the Caucasus, and the South China Sea to command hydrocarbon reserves and pipeline corridors. In the 21st century, the foundational input of military, economic, and cognitive power projection is not pumped from sedimentary basins, but etched with sub-nanometer precision onto 300mm wafers of silicon purified to 99.9999999% (nine nines): semiconductor integrated circuits.
“World War II was decided by steel, aluminum, and oil; the Cold War by thermonuclear warheads; the 21st-century competition between the United States and China will be decided by computing power and physical command over the silicon supply chain.”
The People's Republic of China imports over $400 billion worth of integrated circuits annually — a foreign exchange outlay exceeding its combined imports of crude oil, iron ore, and agricultural commodities. That structural dependency explains why semiconductors have moved from electrical engineering textbooks to the absolute center of national security doctrine in both the White House Situation Room and Beijing's Zhongnanhai. Without frontier AI accelerators (GPUs and TPUs fabricated on 3-nanometer and 2-nanometer nodes) and High-Bandwidth Memory (HBM3e / HBM4), no state can train frontier Artificial Intelligence models, operate AESA (Active Electronically Scanned Array) radar grids, guide hypersonic cruise missiles, or run post-quantum cryptography and algorithmic clearing across global capital markets.
---
II. The Most Complex and Geographically Concentrated Supply Chain in History
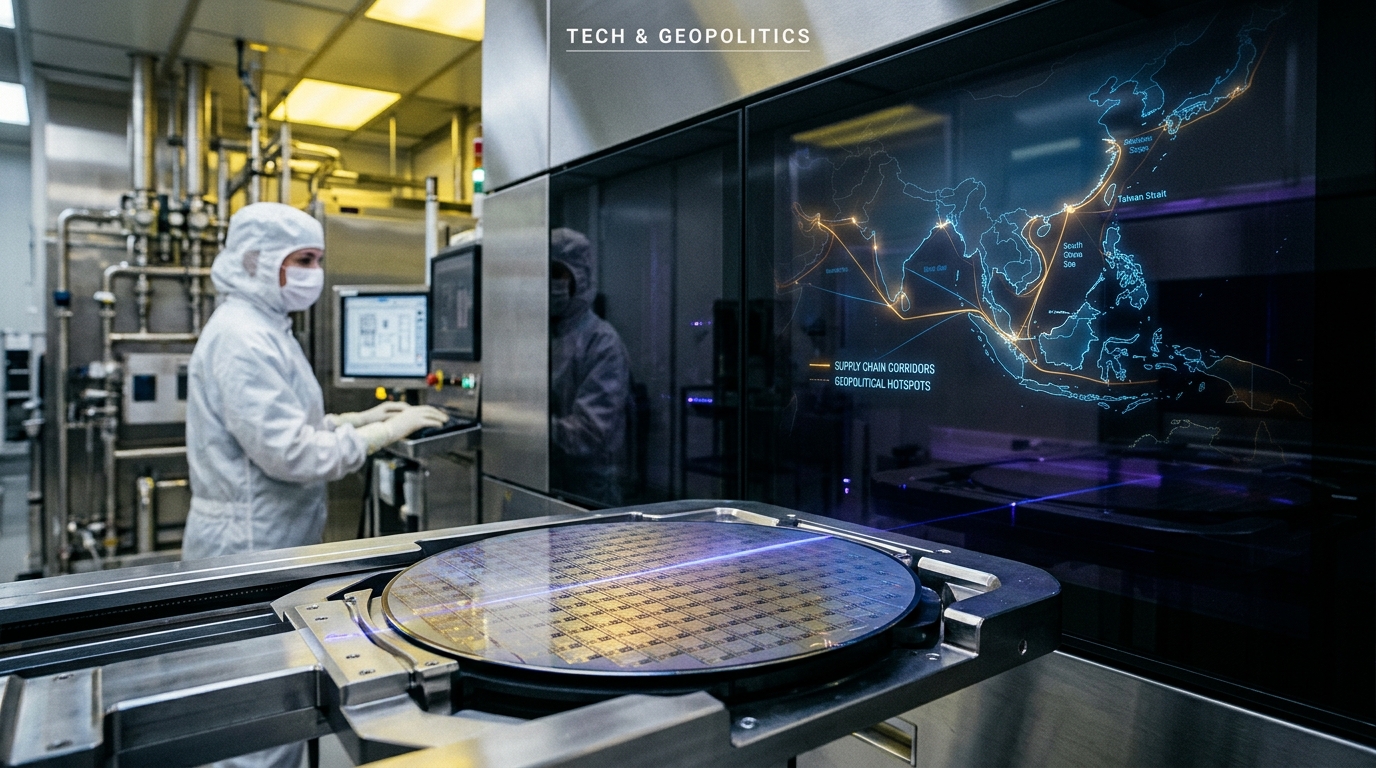
Unlike petroleum refining or steelmaking — where dozens of nations possess domestic reserves and processing capacity — a single frontier logic microprocessor is the most complex manufactured artifact ever engineered by humanity. Its creation requires over 1,200 distinct physical and chemical processing steps distributed across a transnational network where each critical node is controlled by a near-absolute monopoly or oligopoly:
Global Share of Advanced Semiconductor Foundry Capacity (< 7nm)
Extreme geographic concentration situated just 100 miles off the Chinese mainland coast
Deconstructing this value chain reveals five technological chokepoints that no single country has yet replicated domestically:
| Semiconductor Value Chain Node | Dominant Global Champions | Sovereign Jurisdiction | Global Market Share | Entry Barrier & Strategic Vulnerability | | :--- | :--- | :--- | :--- | :--- | | 1. Electronic Design Automation (EDA) & IP | Synopsys, Cadence, Mentor (Siemens) & ARM | United States & United Kingdom | ~85% Global | Impossible to design multi-billion-transistor chips without US software | | 2. Extreme Ultraviolet Lithography (EUV) | ASML Holding (Zeiss Optics / Cymer Lasers) | Netherlands (Germany & USA) | 100% Monopoly | 180-ton systems comprising over 100,000 custom-engineered components | | 3. Ultra-Pure Photoresists, Chemicals & Wafers | Shin-Etsu, SUMCO, Tokyo Ohka Kogyo, JSR | Japan | ~75% to 90% | Parts-per-trillion chemical purity refined over four decades of R&D | | 4. Atomic Deposition, Etching & Metrology | Applied Materials, Lam Research, KLA, Tokyo Electron | United States & Japan | ~80% Global | Atomic-scale plasma engineering subject to strict US BIS export rules | | 5. Pure-Play Advanced Foundry (<5nm) | TSMC (Taiwan Semiconductor Mfg. Co.) | Taiwan (Hsinchu / Tainan) | ~90% in <5nm | Unmatched wafer yield rates and hyper-specialized engineering cluster |
---
III. The Veldhoven Chokepoint: ASML's Impossible Physics and Containment Statecraft
If TSMC in Taiwan is the world's foundry, the Dutch municipality of Veldhoven holds the master key to digital modernity. Headquartered there is ASML, the sole company on Earth capable of manufacturing Extreme Ultraviolet (*EUV* and *High-NA EUV*) lithography machines, whose latest systems cost between $250 million and $380 million per unit and require three Boeing 747 freighters to ship.
To print transistor features smaller than a virus onto silicon, an EUV system performs a feat of physics bordering on science fiction: a high-power carbon dioxide laser built in the United States (by ASML's San Diego subsidiary, Cymer) fires twice per microsecond at 50,000 microscopic droplets of molten tin per second inside a vacuum chamber, vaporizing them into plasma five times hotter than the surface of the Sun to emit extreme ultraviolet light with a wavelength of just 13.5 nanometers. That light is then reflected off multilayer mirrors engineered by Germany's Carl Zeiss — the flattest surfaces ever polished by human hands, such that if a Zeiss mirror were scaled to the size of Germany, its highest irregularity would measure less than one millimeter.
Timeline: Escalation of the Geopolitical Silicon War
Morris Chang Founds TSMC in Hsinchu, Taiwan
Backed by Taipei's industrial policy and initial technology transfer from Philips, Morris Chang pioneers the 'pure-play foundry' model: a fab that never competes with its fabless customers (Apple, Nvidia, AMD).
Huawei Entity List Sanctions and the Foreign Direct Product Rule (FDPR)
Washington invokes the extraterritorial FDPR to bar TSMC from fabricating Kirin processors designed by Huawei's HiSilicon unit because the designs utilized US EDA software.
Sweeping US BIS Export Controls and the US–Dutch–Japanese Pact
The US Commerce Department bans exports of advanced AI GPUs (Nvidia A100/H100) and advanced fab equipment to China, while prohibiting US persons from supporting advanced Chinese semiconductor fabrication.
China's Asymmetric Counter-Offensive and Critical Mineral Controls
SMIC mass-produces 7nm chips via multi-patterning DUV lithography, while Beijing imposes export licensing on Gallium, Germanium, and Rare Earths vital for semiconductor manufacturing.
---
IV. Beijing's Counter-Offensive: Mature Nodes, Multi-Patterning, and Gallium Leverage
The technological containment doctrine articulated by Washington — termed "small yard, high fence" — rested on the premise that denying China access to ASML's EUV lithography and US EDA software would permanently freeze Chinese progress in frontier AI and military supercomputing. Yet industrial developments between 2023 and 2026 have exposed three strategic counter-dynamics:
1. Engineering Around the Blockade via *DUV Multi-Patterning*: Denied EUV systems, China's leading foundry SMIC, working alongside Huawei, leveraged existing 193nm immersion Deep Ultraviolet (DUV) lithography paired with Self-Aligned Quadruple Patterning (SAQP) to manufacture commercial 7-nanometer and 5-nanometer-class processors (powering Huawei's Kirin chips and Ascend 910B/910C AI accelerators), absorbing lower wafer yields as a national strategic cost. 2. Chinese Dominance in Legacy & Power Semiconductors (*Mature Nodes* ≥ 28nm): While Western subsidies focused overwhelmingly on sub-5nm logic, China built dozens of mega-fabs to command global production of 28nm–90nm legacy chips as well as third-generation Silicon Carbide (SiC) and Gallium Nitride (GaN) power semiconductors. These foundational chips are indispensable for electric vehicles, solar inverters, smart grids, civil aviation, and guided munitions — creating a reverse dependency for Western automotive and defense manufacturers. 3. The Upstream Chemical Counter-Chokepoint (Gallium & Germanium): China controls 98% of global primary Gallium production and over 60% of refined Germanium, elements essential for compound semiconductor wafers, military radar modules, and fiber-optic transceivers. By enforcing export controls on these critical elements, Beijing demonstrated that every semiconductor supply chain begins with the periodic table and mineral refining.
---
V. Conclusion: The Paradox of Taiwan's "Silicon Shield"
For four decades, strategists in Taipei maintained that TSMC's near-monopoly functioned as Taiwan's ultimate "Silicon Shield": because both the United States and China depended so heavily on fabrication plants in Hsinchu, Taichung, and Tainan, any military conflict across the Taiwan Strait would trigger an immediate global economic depression — estimated by Bloomberg Economics at a $10 trillion blow (roughly 10% of global GDP) in the first year alone, surpassing the 2008 Global Financial Crisis and the 2020 pandemic combined.
Yet the aggressive reshoring campaign financed by the US CHIPS Act and the European Chips Act — compelling TSMC and Samsung to construct multi-billion-dollar fabrication complexes in Arizona, Kumamoto (Japan), and Dresden (Germany) — introduces the defining geopolitical paradox of the decade: the more successful the West becomes in replicating advanced semiconductor fabrication outside Taiwan to mitigate supply chain risk, the lower the relative economic deterrent against a kinetic crisis in the Taiwan Strait.
The semiconductor war proves that in the 21st century, neither financial nor military sovereignty can exist without industrial sovereignty over the atom and the electron.
Fontes & Referências Documentais
- Miller, Chris (2022). "Chip War: The Fight for the World's Most Critical Technology". Scribner.
- Allison, Graham & Schmidt, Eric (2021). "The Great Tech Rivalry: China vs. the U.S.". Belfer Center for Science and International Affairs, Harvard University.
- Semiconductor Industry Association (SIA) & Boston Consulting Group (BCG) (2024). "Strengthening the Global Semiconductor Supply Chain in an Uncertain Era". SIA-BCG Joint Report.
- Center for Strategic and International Studies (CSIS) (2023). "Choking Off China's Access to the Future of AI: Export Controls and Semiconductor Geopolitics". CSIS Wadhwani Center for AI and Advanced Technologies.
- ASML Holding N.V. (2025). "Extreme Ultraviolet (EUV) & High-NA Lithography Technical Architecture Overview". ASML Veldhoven Technical Whitepapers.